Note X01 Revision 1 Terms read 16 October 2026
Crypto casino: a balance counted in one unit, taken away in another
A £25.00 credit at ten times is expected to reach the door worth £15.00. A flat 50p then comes off it whatever its size, and a five per cent shift in the unit a balance is held in moves 75p, half again as much as the charge. Neither is the expensive part. A smallest payout written as a quantity of units rather than as a sum of money can rise through a balance, and when it does the residue stops being 50p and becomes all of it.
The face £25.00 credited What draws it down £10.00 cleared What is stranded £1.25 at the door
What a face of this size is worth
Every destination on this rack is bought advertising. The site takes a fee if a reader goes on to register, and no figure printed below moves because of it.
Face and Residue
Strip No 01
Betportal
Ceiling as a multiple
Priced at this site's own 10p a spin
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Anjouan, Comoros, run by BetPortal Gaming Ltd, with Excite Ultra Media Ltd, reference ALSI-202601040-FI2.
Terms read 16 October 2026
Open the offer at Betportal, opens in a new tabFace and Residue
Strip No 02
WinBeast
Ceiling as a sum
Priced at this site's own 10p a spin
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Curaçao, operator not named on the site.
Terms read 16 October 2026
Open the offer at WinBeast, opens in a new tabFace and Residue
Strip No 03
EliteSpin
Longest spin window
Priced at this site's own 10p a spin
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Costa Rica, run by PrimeTier Limited.
Terms read 16 October 2026
Open the offer at EliteSpin, opens in a new tabFace and Residue
Strip No 04
Crown Jewelz
Multiple unpublished
No residue struck
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Curaçao, number not verified, operator not named on the site.
Terms read 16 October 2026
Open the offer at Crown Jewelz, opens in a new tabThe two figures in the second and third registers are this site's own arithmetic and nothing an operator has published: the face as printed, less the share a spin gives back at 96 per cent return to player, less what playing the wagering through costs at the same return, and then less whatever a published ceiling, a charge on the way out or a floor on the smallest withdrawal takes off what survives that. The residue is what is left of the face when all of it is accounted for. It describes the offer, not one reader's afternoon. Where the conditions price above the face the strip prints nothing coming off rather than a negative sum, and where a figure the sum needs is unpublished it prints the condition in the operator's words instead.
A face paid as spins has no unit of its own, so one is supplied. Where an operator publishes what a spin of its own is worth, that figure stands in the first register's own line and is labelled as theirs. Where it does not, this site's own 10p a spin stands there and says so, and every figure below moves in proportion: at half the price, half the money. The share of the face that does come off is also given as pence in the pound, which is the figure that compares a large face against a small one.
Money goes onto a prepaid voucher in fixed denominations, so a smallest deposit published in pounds is rounded up to the first rung of the ladder this site works in, £10, £20, £25, £50, £75 and £100, and the strip prints what that rounding strands. That is the reader's own money and it is never netted into a residue. A smallest deposit published in euros is printed as the operator publishes it, because the ladder here is a sterling one and rounding a euro sum to it would be an invented figure.
Three words stand in the amount column where no figure can. Noted is a published condition that takes value away without leaving the sum a figure to take. Unpriced is a condition whose figure nobody has published, or a credit that is not a sum until a deposit of your own sets it. Own money is money of yours, which is never part of a residue.
Not one of the operators printed above holds a Great Britain licence, so the duties that licence carries do not reach them. All online gambling companies licensed in Great Britain must be part of Gamstop Online, and a reader who has shut themselves out through the scheme is therefore not shut out here. The ceiling of ten times the bonus funds on a wagering requirement, in force since 19 January 2026 under Social Responsibility Code 5.1.1, is a condition of that licence and binds the companies that hold one. On an unlicensed site the Gambling Commission describes consumers as facing unfair gaming practices, financial loss and a lack of recourse if things go wrong, and it names blocked payouts and withdrawal limits set so high they are unattainable among what it has seen. Nobody under 18 may hold an account at any of them.
Every term printed on a strip is the operator's own, and each strip carries the day it was read. The oldest of those readings is 16 October 2026. What binds a reader is the operator's own full terms, and not a line printed here.
1
Two exits, and one of them is not the game’s
Spending a credit down is one piece of arithmetic. Getting what survives into a bank is another, and the second is where a residue stops being a forecast. Until a payout is asked for, a stranded figure is a prediction. Afterwards it is the amount that never left.
Three deductions wait at that door and no two behave alike. A smallest payout is all or nothing: a balance beneath it is held entire, so the loss is not a slice of the sum but the sum. A fixed charge ignores size, which makes 50p a tenth of £5.00 and a two-hundredth of £100.00. And a unit that is not sterling adds a deduction with no sign on it, because the sterling worth of what was asked for is not the sterling worth of what lands.
House figures throughout: 10p a press, 96 pence back for every pound staked, a weighting of one, six prepaid denominations running from £10.00 to £100.00, and the play-through multiple named wherever it is used. Charges, floors and unit prices are modelled parameters, said to be so each time, for the reason part 9 sets out.
| The deduction | What it takes | As the sum rises |
|---|---|---|
| A smallest payout | All of a balance beneath it | Stops biting once cleared |
| A fixed charge | The same cash, always | Shrinks as a share, never in cash |
| A charge set as a slice | A constant share | Holds the share, grows in cash |
| A shift in the unit | A share, either direction | Holds the share, grows in cash |
| A cap on one payment | Nothing of itself | Multiplies what one payment costs |
A counter pricing a balance in units holds no Great Britain licence, and £1.25 of that £25.00 is what the absence costs at the door on the modelled figures used here. Part 7 sets out the exit duties a British licence writes, one short line each, and part 9 adds the single charge that follows a British player wherever a counter is registered.
A residue, on this site, is the part of a printed face that was never coming off: held by a ceiling, held under a floor, rounded past by a denomination, or forfeited by a rule. The door is where those four settle into one number.
2
What £25.00 is expected to be worth by the door
Take the middle rung. A credit of £25.00 carrying ten times has to be staked £250.00 before it turns into money, and four pence in every pound staked is what doing that costs in expectation. Four hundredths of £250.00 is £10.00, so £15.00 is the figure the arithmetic expects to find standing when the staking stops.
Per press the same sum reads differently. A 10p press costs 0.4p in expectation, 2,500 presses satisfy £250.00, and 2,500 lots of 0.4p is £10.00. Licensed reels hold 2.5 seconds between cycles, which puts 6,250 seconds behind that obligation: 1 hour 44 minutes 10 seconds without a break in it. Away from that minimum the same 2,500 presses can be served faster. Faster is not cheaper. It delivers the same 0.4p a press sooner.
Write the survivor as E = B(1 − 0.04W) and the ladder becomes a straight line. Ten times keeps three fifths. Fifteen keeps two fifths. Twenty keeps one fifth. Twenty-five keeps nothing, 0.04 going into 1 exactly that many times, and beyond it the bracket turns negative.
| Credit | Ten times | Fifteen times | Twenty times | Clears a £10.00 floor at |
|---|---|---|---|---|
| £10.00 | £6.00 | £4.00 | £2.00 | No multiple whatever |
| £20.00 | £12.00 | £8.00 | £4.00 | Nothing above twelve and a half |
| £25.00 | £15.00 | £10.00 | £5.00 | Fifteen, to the penny |
| £50.00 | £30.00 | £20.00 | £10.00 | Twenty, to the penny |
| £75.00 | £45.00 | £30.00 | £15.00 | Twenty-one and two thirds |
| £100.00 | £60.00 | £40.00 | £20.00 | Twenty-two and a half |
That last column belongs to the door rather than to the game, and it is the whole point of this section. A multiple says what fraction survives. A floor converts the fraction into a yes or a no. Three fifths of ten pounds is six pounds, six is under ten, and so the bottom denomination answers no at every multiple there is.
0.4p of expected cost a press, 2,500 presses, £10.00 gone
3
A floor written in units is a floor that moves
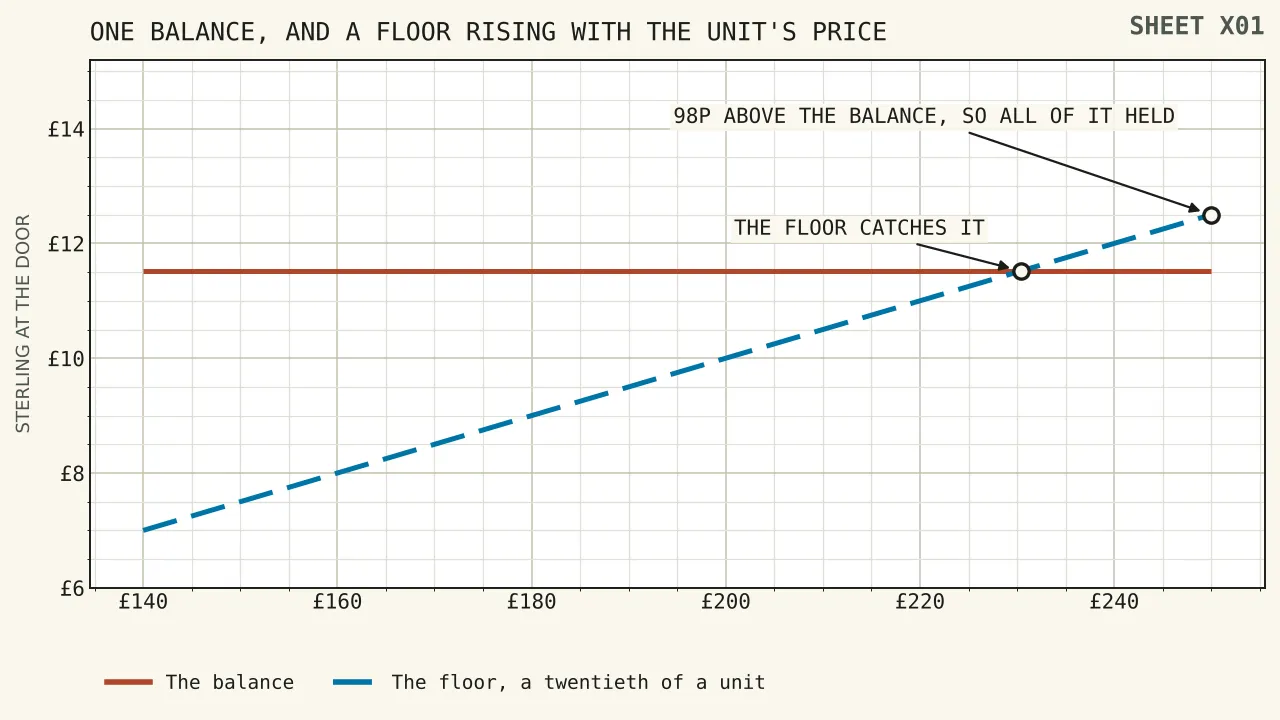
Here is the deduction with no equivalent on a sterling rail. Where a smallest payout is written as a quantity of some unit instead of as a sum of money, its size in pounds is whatever that unit happens to fetch on the day a reader asks. The floor has not moved. The distance to it has.
Model it. A smallest payout of one twentieth of a unit, and a unit at £200.00, make a floor of £10.00: the bottom denomination on this site’s ladder, and the floor figure used throughout. Now move the unit and leave every other number alone. The balance under test is £11.52, which is what a £20.00 credit leaves after ten times once the edge has taken its 80p of the face.
| Unit fetches | Shift against the model | Floor becomes | A £11.52 balance | Residue |
|---|---|---|---|---|
| £140.00 | Down three tenths | £7.00 | Pays, by £4.52 | £0.50 |
| £160.00 | Down a fifth | £8.00 | Pays, by £3.52 | £0.50 |
| £200.00 | The model itself | £10.00 | Pays, by £1.52 | £0.50 |
| £230.00 | Up fifteen hundredths | £11.50 | Pays, by 2p | £0.50 |
| £250.00 | Up a quarter | £12.50 | Held, by 98p | £11.52 |
The bottom two rows are the sharpest arithmetic on this page. A unit at £230.00 leaves a residue of 50p. The same unit at £250.00 leaves a residue of £11.52. One of those is a charge and the other is everything, the step between them is a multiple of 23.04, and nothing about the balance, the game, the multiple or the terms changed to produce it. Ninety-eight pence of distance did all of it.
The favourable direction deserves its own sentence, because a page printing only the bad one is not doing arithmetic. A unit falling a fifth drops the same floor to £8.00 and lets smaller balances out. What a reader cannot choose is which direction is live when a request goes in, and the asymmetry lies in the consequences and not in the odds: a kind shift saves pence off a charge, while an unkind one can hold a whole balance back.
A smaller version of the same effect sits on the sum rather than on the floor. Five per cent either way on £15.00 is 75p, against a modelled charge of 50p. Three per cent is 45p. Ten per cent is £1.50, which is three charges. On this rail the published deduction is routinely the smaller of the two.
4
Fifty pence, indifferent to the size of the sum
A fixed charge is the easiest deduction to underrate, because the cash looks small beside any balance worth moving. Its cost is not the cash. Its cost is the share, and the share is set by the sum rather than by the charge.
Fifty pence takes a tenth of £5.00. It takes 5.79 per cent of £8.64, which is what ten times leaves of a £15.00 credit. It takes two per cent of £25.00 and half a per cent of £100.00. Across that whole range the charge never altered. What altered was the number it was divided into.
| Balance | Share taken | Cheaper shape |
|---|---|---|
| £5.00 | A tenth | A two per cent slice, at 10p |
| £8.64 | 5.79 per cent | A two per cent slice, at 17p |
| £15.00 | 3.33 per cent | A two per cent slice, at 30p |
| £25.00 | Two per cent | Neither, the two are level |
| £50.00 | One per cent | The fixed charge, by 50p |
| £100.00 | Half a per cent | The fixed charge, by £1.50 |
The third column holds this section’s crossing point. Fifty pence and a two per cent slice cost the same thing at £25.00 exactly, since 50p divided by 0.02 is twenty-five pounds. Beneath that sum the slice is cheaper and above it the fixed charge is, and the gap widens in both directions: £2.00 against 50p on a hundred pound payout, 10p against 50p on a five pound one.
Two translations make the figure concrete. At 10p a press, 50p is five presses, and at the licensed pace those five presses take 12.5 seconds. Expressed as credit rather than as balance it gets dearer the heavier the play-through, because covering it takes 50p over the same bracket, c ÷ (1 − 0.04W): 83p of credit at ten times, £2.50 at twenty, £12.50 at twenty-four. A charge at the end of a long obligation is levered by that obligation, and the lever is the same bracket that governs the survivor.
Repetition is the other way a fixed charge gets expensive. Twelve payouts a year at 50p is £6.00, which is three fifths of the bottom denomination on the ladder. Fifty-two of them is £26.00, which is a whole rung and a penny over. Neither figure depends on how much money moved.
5
The smallest credit that reaches the door
Put a floor and a charge together and a question answers itself. What is the smallest credit expected to produce a payable balance? It is (F + c) ÷ (1 − 0.04W), the floor and the charge over that bracket again.
With a £10.00 floor and no charge, that smallest credit is £12.50 at five times, £16.67 at ten, £20.00 at twelve and a half, £25.00 at fifteen, £50.00 at twenty, £83.33 at twenty-two and £250.00 at twenty-four. At twenty-five there is no answer at all, because the divisor is zero and no credit of any size is expected to clear anything. Add the modelled 50p and every figure rises, since the requirement becomes £10.50 of surviving balance rather than £10.00.
| Multiple | Floor alone | Nearest rung above it | Floor and charge | Rung answering both |
|---|---|---|---|---|
| Five times | £12.50 | The twenty pound step | £13.13 | The twenty pound step |
| Ten times | £16.67 | The twenty pound step | £17.50 | The twenty pound step |
| Twelve and a half | £20.00 | That step, to the penny | £21.00 | The twenty-five pound step |
| Fifteen times | £25.00 | That step, to the penny | £26.25 | The fifty pound step |
| Twenty times | £50.00 | That step, to the penny | £52.50 | The seventy-five pound step |
| Twenty-two times | £83.33 | The hundred pound step | £87.50 | The hundred pound step |
| Twenty-four times | £250.00 | Over the top of the ladder | £262.50 | Nothing on the ladder |
Three rows there land on the floor to the penny, and an exact hit is where a near miss does its best work. Twelve and a half times on the twenty pound step, fifteen on the twenty-five pound step and twenty on the fifty pound step each produce a survivor equal to the floor. Each of them fails the instant a charge is introduced. A balance equal to a floor is not a payable balance once anything at all comes off it, so the column that reads like three successes becomes three failures one column to its right.
Notice what that does to the bottom of the ladder. The ten pound step leaves £6.00 at ten times, which is held entire, and no multiple rescues it. A reader buying the smallest denomination available is buying one whose expected survivor is stranded by arithmetic rather than by anybody’s decision, and the stranding is 100 per cent of it rather than a share of it.
£16.67 is the smallest credit expected to clear a £10.00 floor at ten times
6
What each rung hands over, net of both
The two previous parts can be run together into one table, which is the most useful page of arithmetic here for a reader deciding which denomination to buy. Take the expected survivor, test it against a £10.00 floor, take 50p off whatever passes, and print what reaches a bank.
| Credit | Multiple | Survivor | Floor test | Received | Residue against the face |
|---|---|---|---|---|---|
| £10.00 | Ten times | £6.00 | Held | £0.00 | All of it |
| £20.00 | Ten times | £12.00 | Pays | £11.50 | £8.50, or 42.50 per cent |
| £25.00 | Ten times | £15.00 | Pays | £14.50 | £10.50, or 42.00 per cent |
| £25.00 | Fifteen times | £10.00 | Pays by nothing | £9.50 | £15.50, or 62.00 per cent |
| £50.00 | Ten times | £30.00 | Pays | £29.50 | £20.50, or 41.00 per cent |
| £50.00 | Twenty times | £10.00 | Pays by nothing | £9.50 | £40.50, or 81.00 per cent |
| £75.00 | Ten times | £45.00 | Pays | £44.50 | £30.50, or 40.67 per cent |
| £100.00 | Ten times | £60.00 | Pays | £59.50 | £40.50, or 40.50 per cent |
Two rows in that table say “pays by nothing” and they are the ones to look at twice. A survivor of exactly £10.00 passes a £10.00 floor and then hands over £9.50, which is less than the floor it just cleared. The cashier is not at fault and no rule has been broken. The charge simply applies after the test rather than before it, and a reader who had planned around the floor has planned around the wrong figure by 50p.
The last column is the residue as a share of the face, and it settles into a band. At ten times it sits between 40.50 and 42.50 per cent across every rung from twenty pounds upward, which is the four tenths the edge and the multiple take, plus the charge’s shrinking contribution. At the bottom rung it is 100 per cent. At fifteen and twenty times on the rungs that only just clear, it is 62.00 and 81.00 per cent. The spread of that column, 40.50 to 100 per cent, is the practical answer to what a face of this kind is worth, and it is decided at the door and not inside the game.
7
Exit rules a licence writes, in one column
A British licence is specific about this door, and a reader comparing counters is better served by a list than by an adjective. Each line below is a published duty, set against the figure on this page that it governs.
| What it governs | The published position | What it is worth here |
|---|---|---|
| A ceiling on payouts | Barred, on a deposit balance | One charge, not an instalment ladder |
| The regulator’s example of one | Fifty a day, five hundred a week | Forty payments on a two thousand pound balance |
| A floor under payouts | Not barred; reasonableness is the test | The £10.00 floor in part 5 stands |
| Cancelling a request | May not be offered | A requested payout cannot go back to a reel |
| Friction at the exit | To be minimised, says the guidance | No figure attaches, so none is given |
| Documents at the till | Not where they could have been asked earlier | Identity cannot become a deduction |
| A payout held for documents | May put the operator in breach | A breach question, not a fee question |
| A win cap on a credit | Untouched by that bar, being about deposits | A capped credit and a free balance coexist |
| Identity, before a first stake | Three fields, verified up front | Never a deduction at the exit |
The eighth row repays a second reading, being the pairing most often confused. A ceiling on what a credit can turn into is a different object from a ceiling on what a deposit balance can pay out. The second is barred and the first is not, so terms can honestly carry a cap on winnings from a promotion alongside an unrestricted right to take out deposited money. A page merging those two has mislabelled one of them.
None of those duties reaches a counter pricing balances in units, each being fastened to a Great Britain licence alone. The absence is not a judgement about honesty. It is a list of figures nobody has undertaken to hold: no ceiling over a play-through, so the twenty-five times line in part 2 is not a boundary; no ceiling on one payment, so instalment arithmetic applies; no limit on when documents may first be asked for, so the clock in part 8 can start late; and no adjudicator approved by the British regulator at the end of it.
One enforcement outcome belongs beside that list, and it is about a term rather than a payout. On 3 July 2025 a £170,000 penalty landed on the operator trading as Fafabet over a single bonus rule: a discretion, reserved to itself, over closing accounts and taking winnings back. Unfair terms were the finding, the fair and open condition the one breached, and an independent audit of controls over money laundering and safer gambling was ordered with it. Note what the case produced. A fine, not a clause struck out, so a term of that shape is not void because one of them has cost somebody £170,000.
8
Pence a day, and a threshold under a claim
Clocks are the part of an exit a reader notices and the hardest part to price, because waiting costs nothing in cash. What can be priced is the sum held per day of holding. Eight weeks is 56 days, so £15.00 held across the whole of a British complaints process has been held at 26.79p a day. The £11.52 balance from part 3 works out at 20.57p. Spread across the 182 days inside which a complaint has to remain possible, £15.00 is 8.24p a day. Nobody levies any of those. They are what a sum is worth while nobody has it.
| The clock | Where it is written | Length | £15.00 held at |
|---|---|---|---|
| First acknowledgement, round-the-clock site | British guidance | 24 hours | £15.00 a day |
| First acknowledgement otherwise | British guidance | Three working days | £5.00 a day |
| Written receipt | Curaçao policy | One week | £2.14 a day |
| Responsible gaming complaint | Curaçao policy | Five business days | £3.00 a day |
| Operator’s own assessment | Curaçao policy | Four weeks, once extendable | 53.57p a day |
| The whole process | Both regimes | Eight weeks | 26.79p a day |
| Window to complain at all | Both regimes | Six months | 8.24p a day |
Two things in that table deserve naming. The first is that the eight weeks and the six months are the same in both regimes, which is why no page here says that a reader off the British register has no route to complain. Curaçao publishes a complaints document that anybody can open, and its outer limits match. The second is that a week of silence on a reasonable information request pauses the British 56 days, which then resume where they halted rather than at nought, so 56 days is a floor under the wait and not a ceiling over it.
The regimes diverge over authorship of the adjudication terms, and that divergence is the line worth a reader’s attention. Approval by the British regulator is the test there, and eight bodies hold it, though cover differs: one of the eight is listed for premises sectors only, which leaves a remote casino player with seven. Curaçao makes adjudication compulsory, free at the point of use, paid for by the operator, and drafted by the operator too. A minimum claim value is among the terms it may fix.
Price that threshold and the shape of the problem appears. Suppose a minimum claim value of £50.00, modelled rather than quoted. The £15.00 survivor of part 2 is 30 per cent of it. The £11.52 balance of part 3 is 23.04 per cent of it. The £6.00 left by the bottom rung is twelve per cent. Each of those has a route that exists, costs nothing, and cannot be used, and the smaller the residue the more certainly that is so. A threshold under a claim is a floor by another name, and it behaves exactly like the floor in part 3: all or nothing, and all of the sum where it bites.
Four words from the British regulator want taking literally: not an ombudsman. No payout dispute settled by it, no money recovered through it, no sight of an account held by it. Its own instruction is the business first, with the approved body as the step after.
9
Four figures, and what this note will not price
One charge at this door is indifferent to where a counter is registered, and it is the one least often mentioned. Remote gaming duty: 40 per cent of gaming profits from 1 April 2026, 21 per cent over the seven years from 1 April 2019, and 15 per cent before that again. The pin is where a customer usually lives, which puts a British player’s balance inside a British tax whichever register has no record of the counter holding it. The operator pays. A player’s own position comes out of an absence instead of a charge, HMRC’s manuals declining to treat betting as a trade in itself, which leaves no trading income for anything to catch. Nothing here is tax advice.
Four dates from the regulator’s own writing carry quantities rather than adjectives. 20 January 2025: a warning notice puts titles from licensed suppliers onto sites holding no British licence, so a familiar game tells a reader about a supplier and nothing at all about a register. 23 July 2026: £4.75m agreed by one licensed supplier whose games had reached six such sites open to consumers here. Then 160 sites targeted for enforcement, with 32 per cent of their traffic gone afterwards, printed beside an admission that the market behind them will probably never be shut down entirely. And 21 October 2025, on this door specifically: two failure modes named by the Director of Enforcement and Intelligence, which were payouts stopped and withdrawal ceilings pitched past reach.
Now the refusals, which are deliberate. Charges, floors and unit prices above are modelled parameters, and they have to be: a distribution of payout charges, of withdrawal ceilings or of wagering multiples away from the British register is published by nobody whose word this site will take. Trade publications and affiliate pages carry all three, and none is citable here. So the method is to name a parameter as a model and then move it, which is why parts 3, 4 and 5 run as ladders instead of single figures.
The contrast needing no number is structural. From 19 January 2026 a British licence holds the multiple at ten, and the object it holds is an obligation to stake a stated total first, money being unwithdrawable until it is met. Open the Curaçao responsible gaming document and none of that is in it: the multiple is uncapped, so is the stake, so is the pace of a cycle, autoplay goes unaddressed, hurrying a result goes unaddressed, and so does the presenting of a return no bigger than what was staked. Incentives get two lines there, transparency and a bar on promotion that drives excessive play, and those two lines are the whole of it. An absence named out of a document a reader can open beats the word unregulated.
This note also declines to say which payment method any counter will take, inward or outward, and runs no comparison of how methods fare where a British licence is absent. No payout speed for a named operator appears, and no promotion code. Nor is there a word here on returning to a site a reader has locked, or on defeating a bank’s gambling block: a line rather than a gap in the research.
If the exclusion scheme is why a reader is here, the useful facts run the other way. Taking part is a condition of holding the British licence, which is what sets the scheme’s reach, and the scheme says for itself that operators outside it are beyond its help. Worth more than any figure above are three things that cost a reader nothing at all.
| What it is | Where it reaches | How to get it |
|---|---|---|
| National Gambling Helpline, run by GamCare | Any hour of any day | 0808 8020 133; a chat window and WhatsApp answer too |
| Gamban, blocking software | Tens of thousands of sites and apps | Through GamCare at no charge, under the name TalkBanStop |
| Gamstop Online, the exclusion scheme | Every British licensed account | Registration at the scheme itself |
Two cautions on that middle row, and both are published. The page announcing the free British route is an article dated 12 April 2021 which puts no duration on the access, so no duration is stated here. And the software’s own site offers a trial of seven days with no British free route named anywhere on it. Those are the two halves of one picture and they belong in the same sentence.
Questions
- What is stranded when a payout floor sits above a balance?
- All of it, which is what separates a floor from a charge. A charge takes a slice and leaves the rest. A £10.00 floor against £8.64 leaves nothing, so the residue is £8.64 and the share stranded is 100 per cent. Nothing in between occurs, and that is why part 3 draws a step rather than a slope.
- Can staking lift a balance over a floor?
- Not in expectation, and the direction is worth being blunt about. Closing a gap of £1.36 means staking, staking costs four pence in the pound, and each circuit of the balance is therefore expected to widen the gap rather than close it. Floors are crossed by variance alone, and the expected residue of a sub-floor balance is the whole of it.
- Why does 50p matter on a sum worth moving?
- Because the share bites and the cash does not. Fifty pence is a tenth of £5.00, 5.79 per cent of £8.64, two per cent of £25.00 and half a per cent of £100.00. Stated as credit rather than as balance it worsens with the obligation: 83p of credit at ten times, £2.50 at twenty, £12.50 at twenty-four.
- Where does a fixed charge beat a slice?
- Above the sum where the two are level, which is the charge divided by the rate. Fifty pence against two per cent levels at £25.00 exactly. Beneath it the slice is cheaper, so a £5.00 payout costs 10p as a slice and 50p flat. Above it the fixed charge wins, so a £100.00 payout costs £2.00 as a slice and 50p flat.
- What is the smallest credit worth taking at ten times?
- Sixteen pounds sixty-seven where a £10.00 floor is the only obstacle, because three fifths of that sum is ten pounds. Add 50p and the answer becomes £17.50. Neither figure is a denomination, so the twenty pound step is the first that answers either, and the ten pound step answers neither at any multiple.
- Why does twenty-five times keep reappearing?
- Because 0.04 goes into 1 precisely twenty-five times. Survivor is E = B(1 − 0.04W), and the bracket closes to zero at twenty-five. No credit of any size, on any rung, is expected to produce a payable balance there, and past it the expectation is a deficit instead of a residue.
- Is a floor written in units against any published rule?
- Nothing on the regulatory sheet behind this site speaks to it. A British licence bars terms that cap payouts out of a deposit balance, the example given of that shape being £50.00 daily alongside £500.00 weekly. A smallest payment is a different object, tested for reasonableness and nothing else. So the floor in part 3 survives the rule and strands £11.52 regardless.
- Can a requested payout be put back into play?
- Not under a British licence, which forbids offering the cancellation of a payout request at all, and whose guidance adds that money once requested is not to come back as a deposit. Away from that licence nothing fixes it, and a reversal then costs four pence in the pound for every turnover it meets: £1.20 on £30.00 for one circuit, £12.00 at ten times, the lot at twenty-five.
- How long can a complaint run, and what is the delay worth?
- Eight weeks at most under a British licence, counted from the day it arrived. Three working days bound the first acknowledgement, cut to 24 hours where a site runs round the clock, while six months after the incident is the shortest window a reader gets for bringing one. A £15.00 balance held across the full 56 days has been held at 26.79p a day. Curaçao’s own document runs four weeks and one four-week extension, which is the same eight.
- What happens to a small claim where a minimum claim value applies?
- It has a route it cannot use. The Curaçao policy lets an operator set the parameters of adjudication, a minimum claim value among them, so a residue is excluded by its size rather than by its merits. Against a modelled threshold of £50.00, the £15.00 survivor reaches 30 per cent of the way and the £6.00 left by the bottom rung reaches twelve. A threshold under a claim behaves exactly like a payout floor.
- Does a British player pay tax on what comes out?
- HMRC’s published position comes out of an absence. Betting is not treated as a trade in itself, which leaves no trading income to tax, and no gov.uk page was found declaring winnings untaxed in so many words. The charge sits on the operator instead, at 40 per cent of gaming profits from 1 April 2026, pinned to where a customer usually lives and not to a licence address. None of this is tax advice.
- Why are the charges here modelled rather than quoted?
- Because nobody citable publishes a distribution of payout charges, of withdrawal ceilings or of wagering multiples away from the British register. Trade publications and affiliate pages carry such figures and none of them is a source here. So each parameter is named as a model and then moved, which is why part 4 tabulates shares and part 5 tabulates multiples. The sourced contrast is structural: ten times binds in Great Britain, and the Curaçao rulebook holds no ceiling of any size.