Note X03 Revision 1 Terms read 16 October 2026
Ethereum casino: a charge per operation, and the count of operations
Where a payout costs a fixed £2.50 each time it happens, the only figure a reader controls is how many times it happens. A ceiling of £50.00 on one payment turns that fixed charge into a five per cent charge on any sum at all, because £2.50 divided by £50.00 is a twentieth. And between £50.00 and £60.00 of balance a reader who empties the ceiling first strands the remainder under a £10.00 floor, which costs up to £5.50 more than splitting the same money evenly.
The face A £25.00 credit What draws it down Ten turnovers, £10.00 What is stranded £12.50, exactly half
What a face of this size is worth
Every destination on this rack is bought advertising. The site takes a fee if a reader goes on to register, and no figure printed below moves because of it.
Face and Residue
Strip No 01
Betportal
Ceiling as a multiple
Priced at this site's own 10p a spin
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Anjouan, Comoros, run by BetPortal Gaming Ltd, with Excite Ultra Media Ltd, reference ALSI-202601040-FI2.
Terms read 16 October 2026
Open the offer at Betportal, opens in a new tabFace and Residue
Strip No 02
WinBeast
Ceiling as a sum
Priced at this site's own 10p a spin
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Curaçao, operator not named on the site.
Terms read 16 October 2026
Open the offer at WinBeast, opens in a new tabFace and Residue
Strip No 03
EliteSpin
Longest spin window
Priced at this site's own 10p a spin
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Costa Rica, run by PrimeTier Limited.
Terms read 16 October 2026
Open the offer at EliteSpin, opens in a new tabFace and Residue
Strip No 04
Crown Jewelz
Multiple unpublished
No residue struck
What is printed
What draws it down
What is stranded
No Great Britain licence
Licensed in Curaçao, number not verified, operator not named on the site.
Terms read 16 October 2026
Open the offer at Crown Jewelz, opens in a new tabThe two figures in the second and third registers are this site's own arithmetic and nothing an operator has published: the face as printed, less the share a spin gives back at 96 per cent return to player, less what playing the wagering through costs at the same return, and then less whatever a published ceiling, a charge on the way out or a floor on the smallest withdrawal takes off what survives that. The residue is what is left of the face when all of it is accounted for. It describes the offer, not one reader's afternoon. Where the conditions price above the face the strip prints nothing coming off rather than a negative sum, and where a figure the sum needs is unpublished it prints the condition in the operator's words instead.
A face paid as spins has no unit of its own, so one is supplied. Where an operator publishes what a spin of its own is worth, that figure stands in the first register's own line and is labelled as theirs. Where it does not, this site's own 10p a spin stands there and says so, and every figure below moves in proportion: at half the price, half the money. The share of the face that does come off is also given as pence in the pound, which is the figure that compares a large face against a small one.
Money goes onto a prepaid voucher in fixed denominations, so a smallest deposit published in pounds is rounded up to the first rung of the ladder this site works in, £10, £20, £25, £50, £75 and £100, and the strip prints what that rounding strands. That is the reader's own money and it is never netted into a residue. A smallest deposit published in euros is printed as the operator publishes it, because the ladder here is a sterling one and rounding a euro sum to it would be an invented figure.
Three words stand in the amount column where no figure can. Noted is a published condition that takes value away without leaving the sum a figure to take. Unpriced is a condition whose figure nobody has published, or a credit that is not a sum until a deposit of your own sets it. Own money is money of yours, which is never part of a residue.
Not one of the operators printed above holds a Great Britain licence, so the duties that licence carries do not reach them. All online gambling companies licensed in Great Britain must be part of Gamstop Online, and a reader who has shut themselves out through the scheme is therefore not shut out here. The ceiling of ten times the bonus funds on a wagering requirement, in force since 19 January 2026 under Social Responsibility Code 5.1.1, is a condition of that licence and binds the companies that hold one. On an unlicensed site the Gambling Commission describes consumers as facing unfair gaming practices, financial loss and a lack of recourse if things go wrong, and it names blocked payouts and withdrawal limits set so high they are unattainable among what it has seen. Nobody under 18 may hold an account at any of them.
Every term printed on a strip is the operator's own, and each strip carries the day it was read. The oldest of those readings is 16 October 2026. What binds a reader is the operator's own full terms, and not a line printed here.
1
The variable is the number of times
A charge levied per payout rather than per pound changes what a reader is deciding. Size stops mattering and frequency starts. Move £100.00 once and the bill is £2.50. Move the same £100.00 in four payments and the bill is £10.00, which is a tenth of the money, for the identical sum arriving in the identical place.
So the arithmetic of this page has one input nobody usually writes down, and that is a count. Three things fix it. A ceiling on a single payment forces the count upward. A floor under a single payment forbids the count going high enough to leave a small remainder. And a reader’s own impatience raises it voluntarily, which is the one of the three that costs money for no reason at all.
Fixed quantities, as on every page here: a press worth 10p, 96 pence returning on each pound staked, a weighting of unity, and six denominations lying between £10.00 and £100.00. One shorthand is used throughout and defined here: the surviving fraction is 1 less four hundredths of the turnover count, so it is three fifths at ten turnovers and two fifths at fifteen. Modelled for this page alone: £2.50 a payout, a floor of £10.00, and a ceiling of £50.00 on any one payment. Part 8 says why those three are parameters and not quotations.
A counter denominating a balance in some unit other than sterling holds no Great Britain licence. What that absence first permits is the ceiling named a paragraph above: under a British licence, a term that puts a maximum over payouts from a deposit balance is barred outright, and the barred shape the regulator prints as its example sets a figure for each day beside a figure for each week. Part 2 prices that pairing.
| What sets it | Which way it pushes | Whose decision |
|---|---|---|
| A ceiling on one payment | Upward, by division | The terms |
| A floor under one payment | Downward, by forbidding a small last one | The terms |
| Wanting part of it now | Upward, by choice | The reader |
| A balance under the floor | To nil, since no payment happens | Neither |
2
A ceiling turns a fixed charge into a rate
This is the finding of the page and it is one division. Where a single payment may not exceed some ceiling, and each payment costs some fixed charge, the charge as a share of any large balance is the charge divided by the ceiling. It no longer shrinks as the sum grows, because the number of payments grows with it.
£2.50 divided by £50.00 is five per cent, and five per cent is therefore what a reader pays on £100.00, on £500.00 and on £2,000.00 alike. The fixed charge has been converted into a proportional one by a rule that says nothing about charges at all.
| Balance | Payments needed | Charged in total | Share of the balance | Had one payment been allowed |
|---|---|---|---|---|
| £50.00 | One | £2.50 | A twentieth | £2.50 |
| £100.00 | Two | £5.00 | A twentieth | £2.50 |
| £200.00 | Four | £10.00 | A twentieth | £2.50 |
| £500.00 | Ten | £25.00 | A twentieth | £2.50 |
| £1,000.00 | Twenty | £50.00 | A twentieth | £2.50 |
| £2,000.00 | Forty | £100.00 | A twentieth | £2.50 |
The fourth column never moves, which is the whole of the point, and the fifth column shows what the ceiling cost. On £2,000.00 the difference between one payment and forty is £97.50, and the money bought nothing: the same balance reached the same place. Expressed as a multiple, the ceiling made the charge forty times what it would otherwise have been, and forty is simply £2,000.00 divided by £50.00.
Now add the clock, because a ceiling on a single payment usually comes with a period attached. In the barred shape the British regulator prints, the day carries £50.00 and the week carries £500.00. Put £2,000.00 through that pairing and it takes forty payments and four weeks, which is 28 days of holding, and the charge is £100.00. Count comes from the daily figure and calendar from the weekly: ten payment days fit inside each week of seven, so the week runs out of days before it runs out of allowance, and four days in every seven are idle by construction.
That term is barred under a British licence and nothing bars it elsewhere, which is the plainest piece of pricing in this section. A reader is not comparing honesty. A reader is comparing whether £97.50 and four weeks are on the table.
£2.50 over a £50.00 ceiling is a five per cent charge on any sum
3
The tail under the floor, and how to avoid it
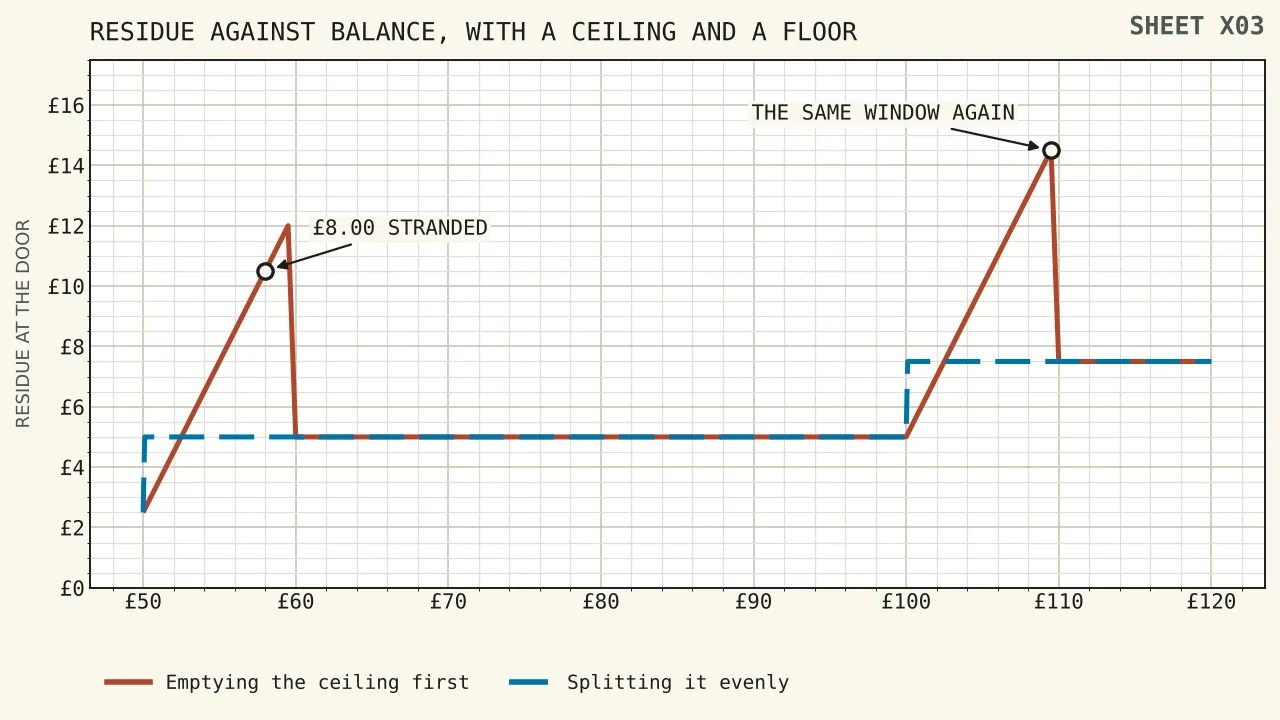
A ceiling and a floor together make a trap with a narrow mouth, and a reader walks into it by doing the obvious thing. The obvious thing is to take the largest payment allowed, then the next largest, and so on until the balance runs out. Call that emptying the ceiling. It is the wrong method whenever the final remainder lands under the floor.
Take a balance of £58.00. Empty the ceiling and £50.00 goes first, leaving £8.00 where the floor stands at £10.00, so it is £2.00 short and unpayable. One charge of £2.50 plus £8.00 stranded is a residue of £10.50, or 18.10 per cent of the balance. Split the same £58.00 into two payments of £29.00 and the residue is two charges, £5.00, or 8.62 per cent. Nothing changed but the arithmetic a reader did first.
| Balance | Emptying the ceiling | Residue that way | Splitting evenly | Residue that way |
|---|---|---|---|---|
| £50.00 | One payment, nothing left | £2.50 | One payment, the same | £2.50 |
| £55.00 | One payment, £5.00 stuck | £7.50 | Two of £27.50 | £5.00 |
| £58.00 | One payment, £8.00 stuck | £10.50 | Two of £29.00 | £5.00 |
| £60.00 | Two payments, nothing left | £5.00 | Two of £30.00 | £5.00 |
| £105.00 | Two payments, £5.00 stuck | £10.00 | Three of £35.00 | £7.50 |
| £120.00 | Three payments, nothing left | £7.50 | Three of £40.00 | £7.50 |
Three rows there show a saving and three show none, and the pattern behind that is exact. Emptying the ceiling is harmless whenever the balance divides into the ceiling with nothing left over, or with at least the floor left over. It costs money in the band between those two, which is to say wherever the balance sits more than a ceiling but less than a ceiling plus a floor above a multiple of the ceiling. On the figures here that band runs from just over £50.00 up to £60.00, then from just over £100.00 up to £110.00, and so on up the scale in ten pound windows.
The fix is a division rather than a judgement. Count the payments as the balance divided by the ceiling, rounded up, then divide the balance by that count. At £58.00 the count is two and the payment is £29.00. At £105.00 the count is three and the payment is £35.00. The method works down to twice the floor, £20.00, below which there is only one payment to make and nothing to arrange.
One warning belongs with that. Nothing here says a counter will accept an instruction of that shape, and nothing here is advice about how to deal with one. It is arithmetic about what the two rules do when they meet, and the reason to print it is that the trap is invisible in the terms: a £50.00 ceiling reads as generous and a £10.00 floor reads as trivial, and between them they can hold £8.00 of a £58.00 balance permanently.
4
£2.50 in presses, seconds and credit
A charge means more when it is converted into the units a reader has been thinking in. Three conversions, all of them from figures fixed elsewhere on this site.
Twenty-five presses, at the 10p stake used throughout. Licensed slots leave 2.5 seconds clear between one cycle and the next, so those presses occupy 62.5 seconds. Four hundredths of 10p is the expected cost of each, which makes 10p across the twenty-five, so the charge comes to twenty-five times the expected cost of the play it would have paid for. A reader paying one payout charge has paid for a minute of reel and lost the minute.
The third conversion bites hardest. A charge standing at the end of a play-through has to be earned through that play-through, so in credit it costs the charge over the surviving fraction.
| Multiple | Credit needed to cover it | As presses |
|---|---|---|
| Ten times | £4.17 | Forty-two presses, near enough |
| Twelve and a half | £5.00 | Fifty presses exactly |
| Fifteen times | £6.25 | Sixty-three presses, near enough |
| Twenty times | £12.50 | A hundred and twenty-five presses |
| Twenty-four times | £62.50 | Six hundred and twenty-five presses |
| Twenty-five times | No figure answers | No number of presses answers |
Twelve and a half turnovers give a clean coincidence: £5.00 of credit covers £2.50 of charge, so the charge costs exactly double in credit what it costs in cash. Twenty turnovers make it five times. Twenty-four make it twenty-five times. A payout charge is levered by the surviving fraction just as the survivor is, and the heavier the obligation the more a flat charge at the end of it actually takes.
5
What each denomination hands over
Run the six denominations through a £10.00 floor and a £2.50 charge, and the table below is what arrives. Survivor is the credit scaled by the surviving fraction. The floor test runs ahead of the charge, and that order does the damage on two of these rows.
| Credit | Turnovers asked | Survivor | Floor test | Into the bank | Residue as a share |
|---|---|---|---|---|---|
| £10.00 | Ten | £6.00 | Held, by £4.00 | Nil | The whole credit |
| £20.00 | Ten | £12.00 | Pays, by £2.00 | £9.50 | 52.50 per cent |
| £25.00 | Ten | £15.00 | Pays, by £5.00 | £12.50 | Exactly half |
| £50.00 | Ten | £30.00 | Pays, by £20.00 | £27.50 | 45.00 per cent |
| £75.00 | Ten | £45.00 | Pays, by £35.00 | £42.50 | 43.33 per cent |
| £100.00 | Ten | £60.00 | Pays, by £50.00 | £57.50 | 42.50 per cent |
| £25.00 | Fifteen | £10.00 | Pays, by nothing | £7.50 | 70.00 per cent |
| £20.00 | Fifteen | £8.00 | Held, by £2.00 | Nil | The whole credit |
Two rows stand out and neither is the bottom one. Clearing the floor by £2.00, the twenty pound denomination at ten turnovers then puts £9.50 into a bank, 50p short of the floor it had just cleared. The twenty-five pound denomination at fifteen turnovers clears the floor by nothing at all and hands over £7.50, which is a quarter under it. In both cases a reader who planned around the floor planned around a figure they were never going to receive.
The residue share falls as the denomination rises, from 52.50 per cent on the twenty pound step to 42.50 per cent on the hundred pound step, and the reason is only that the charge is a smaller fraction of a bigger survivor. The multiple’s own contribution is fixed at two fifths of the credit at ten turnovers, whatever the denomination. So of the 52.50 per cent lost on the twenty pound step, 40 points are the multiple and 12.50 points are a single £2.50 charge.
And the least credit that can be expected to leave a payable balance, on these parameters, is £20.83 at ten turnovers, £25.00 at twelve and a half, £31.25 at fifteen and £62.50 at twenty. None of the first three is a denomination, so a reader wanting a payable balance at ten turnovers is buying the twenty-five pound step and a reader at fifteen turnovers is buying the fifty.
£20.83 of credit to clear a £10.00 floor and a £2.50 charge at ten turnovers
6
Two directions running at two speeds
One structural thing a British licence insists on, and it is about speed rather than money. Limits a customer sets on their own account move at different speeds in the two directions. Loosening one waits; tightening one does not.
| The change | British licence | The Curaçao policy |
|---|---|---|
| Tightening a limit | At once, barring a technical failure | At once |
| Loosening a limit | A day’s cooling off, then a fresh confirmation | Seven days of waiting |
| Periods on offer | A day, seven days and a month, at least | Daily, weekly or monthly |
| Setting one at all | The default choice, declined only by an action | Required to be offered |
| Being prompted to set one | At registration or at a first payment | Among the mandatory subjects |
| A review prompt | Every six months where an account is active | Not specified |
Two things in that table run against what a reader would expect, and both are worth saying plainly. The first is that on this one point the offshore document is the stricter of the two: seven days of waiting before a limit loosens, against a day under a British licence. The second is that the strictness is about deposits rather than payouts, so it does nothing for the figures in parts 2 and 3. A reader who cannot loosen a deposit limit for a week can still face a £50.00 ceiling on the way out, and the two rules never meet.
The asymmetry is the part worth generalising, because the exit has the same shape. A tightening takes effect at once and a loosening waits, which means the quick direction is always the one that reduces what a reader can lose. Compare that with a payout ceiling, where the quick direction is the one that reduces what a reader can take. Same mechanism, opposite beneficiary, and the difference between the two is exactly what a licence is.
7
Two limits meeting, and the £30.00 nobody set
One worked example of two limits meeting is published by the British regulator, and it is arithmetic rather than principle. Hold a daily limit at £10.00 and a weekly one at £100.00 together: whichever binds tighter binds at every moment, so a system has to permit ten pounds across one day and seventy across one week.
Note what has happened to the weekly figure. A reader set £100.00 and gets £70.00, so £30.00 of the limit they chose is unreachable. That £30.00 is a residue of precisely the kind this site exists to print: nobody took it, nobody charged for it, and it was never going to be available, because seven days at ten pounds is seventy pounds and no arrangement of the week changes that.
| What is set | What the week allows | Unreachable |
|---|---|---|
| £10.00 a day, £100.00 a week | Seventy pounds | Thirty pounds of the weekly figure |
| £10.00 a day, £70.00 a week | Seventy pounds | Nothing; the two agree |
| £20.00 a day, £100.00 a week | A hundred pounds | Nothing; the weekly one binds |
| £15.00 a day, £100.00 a week | A hundred pounds | Five pounds of the daily figure, on one day |
The general rule reads off that table in a line. Where seven times the daily figure exceeds the weekly one, the weekly one binds and the daily figure is partly decoration. Where it falls short, the daily figure binds and part of the weekly one is unreachable. The two agree only where the weekly figure is seven times the daily, and a reader setting both without doing that multiplication has set one number that does nothing.
Deposits have to stop once a limit is met, and stay stopped till the period turns over or the customer moves the figure, which brings in the day of cooling off from part 6. So a daily limit beside a weekly one is not two safeguards. It is one safeguard and one number, and a multiplication by seven decides which is which.
8
The absence, priced on one denomination
Take the twenty-five pound denomination through four multiples and the whole case for a ceiling on the multiple appears as four figures. At ten turnovers the survivor is £15.00, which clears the floor and hands over £12.50. At fifteen it is £10.00, which clears by nothing and hands over £7.50. At twenty it is £5.00, which the floor holds in full. At forty it is a deficit of £15.00, meaning the credit is gone and a reader’s own money is £15.00 down behind it. A British licence halts that climb at ten turnovers, and has halted it there since 19 January 2026.
The same denomination makes the other half of the point. On the figures above, the difference between a capped multiple and an uncapped one on one twenty-five pound credit runs from £12.50 received to £15.00 lost, a span of £27.50 on a face of £25.00. So one uncapped number can be worth more than the whole credit carrying it.
What the Curaçao responsible gaming document holds on all of this is worth stating by naming the absences rather than by using the word unregulated. There is no ceiling on the multiple in it. There is nothing on a payout charge, nothing on a payout ceiling, nothing on a payout floor, and nothing on how many payments a balance may be broken into. Incentives get two sentences there, the first asking that terms be put transparently and the second forbidding aggressive promotion of them. One duty that document does carry, which the British advertising rules do not, falls on affiliates: an operator is answerable for them through binding contracts, compliance audits and penalties.
Three refusals, in the frame this page uses. First, every charge, ceiling and floor above is a parameter rather than a quotation, because how such figures are distributed off the British register is published nowhere citable, and a ladder that moves beats a single invented number. Second, no payout speed is given here for anybody, and no promotion code. Third, nothing here identifies a payment method any counter will accept, inward or outward, and nothing here touches the reopening of a site a reader has shut, or the defeat of a bank’s gambling block.
On that last point the useful material runs the other way and it is short. The national exclusion scheme is reached through the British licence, since every company holding one has to belong, which is why the scheme says for itself that companies standing outside are past its help. Calling the National Gambling Helpline costs nothing and somebody answers at any hour. The care block below this carries the number, and the note on faces sold away from the register sets out both the blocking software and the cost-free British way to it.
Questions
- Why does a fixed payout charge behave like a percentage?
- Because a ceiling on one payment makes the number of payments rise with the balance. Divide the charge by the ceiling and the rate falls out: £2.50 over £50.00 is five per cent, and five per cent is what a reader pays on £100.00, on £500.00 and on £2,000.00 alike. The charge stopped shrinking the moment the ceiling appeared.
- What does a £50.00-a-day ceiling cost on £2,000.00?
- Forty payments, four weeks and £100.00 at £2.50 a payment, against £2.50 for a single payment of the whole sum. So the ceiling cost £97.50 and 28 days, and the money bought nothing at all: the same balance reached the same place. A term of that exact shape, pairing a daily figure with a weekly one, is barred under a British licence.
- Why not just take the biggest payment allowed each time?
- Because the last remainder can land under the floor. On a £58.00 balance, taking £50.00 first leaves £8.00 where the floor stands at £10.00, so one charge and a stuck £8.00 come to a residue of £10.50. Two payments of £29.00 cost two charges, £5.00. The saving is £5.50 and the only difference is a division done beforehand.
- Which balances fall into that trap?
- Those sitting between a multiple of the ceiling and that multiple plus the floor. On these figures the windows run from just over £50.00 to £60.00, then just over £100.00 to £110.00, and so on in ten pound bands up the scale. Outside those windows, emptying the ceiling costs exactly what splitting evenly costs.
- How is the safe split worked out?
- Divide the balance by the ceiling and round up, then divide the balance by that count. At £58.00 the count is two and each payment is £29.00. At £105.00 the count is three and each is £35.00. It works down to twice the floor, £20.00, below which one payment is the only option and there is nothing to arrange.
- What is £2.50 worth in play?
- Twenty-five presses at the 10p stake used here. Licensed slots keep 2.5 seconds clear between cycles, so those presses fill 62.5 seconds, and they carry 10p of expected cost between them. One payout charge therefore costs twenty-five times the play it would have paid for.
- How much credit does a £2.50 charge really cost?
- More than £2.50, since it has to be earned through the play-through first. Divide by the surviving fraction and the answers are £4.17 at ten turnovers, £5.00 at twelve and a half, £6.25 at fifteen, £12.50 at twenty and £62.50 at twenty-four. At twenty-five nothing answers, the fraction having closed to nought.
- Which denominations pay out under these parameters?
- Five of the six at ten turnovers. The ten pound step leaves £6.00 and is held in full. The twenty pound step clears the floor by £2.00 and hands over £9.50, which is under the floor it cleared. The twenty-five pound step hands over £12.50, exactly half the face, and the figures improve slowly from there to 42.50 per cent on the hundred pound step.
- Why is a deposit limit quicker to tighten than to loosen?
- Because the rules are written that way, and on both sides of the register. A tightening takes effect at once under a British licence, barring technical failure, while a loosening waits a day and then needs confirming again. The Curaçao document is stricter still on that point, making a loosening wait seven days, and neither rule touches what happens on the way out.
- What happens when a daily limit meets a weekly one?
- Whichever binds tighter binds at every moment. Hold £10.00 to a day and £100.00 to a week and seventy pounds is what the week allows, leaving £30.00 of a reader’s own chosen figure out of reach. The pair agree only where the weekly one is seven times the daily one, and setting both without that multiplication leaves one of them doing nothing.
- What is an uncapped multiple worth on a £25.00 credit?
- A span of £27.50, which is more than the credit. Ten turnovers hand over £12.50. Fifteen hand over £7.50. Twenty leave £5.00, which the floor holds in full. Forty are expected to finish £15.00 beyond the end of the credit, which is a reader’s own money going after it.
- Are the charges and ceilings here quoted from anywhere?
- No, and each says so where it appears. Nobody citable here publishes how payout charges, ceilings and floors are distributed off the British register, so every one of them is a parameter to be moved rather than a figure to be asserted. What is sourced is the structure: ten turnovers caps a British multiple, and no cap of any size sits in the Curaçao document.